Brown & Brown (BRO) Flashes a Green Sign Amidst a Downtrend: Is Deep Undervaluation Fueling This Surge?
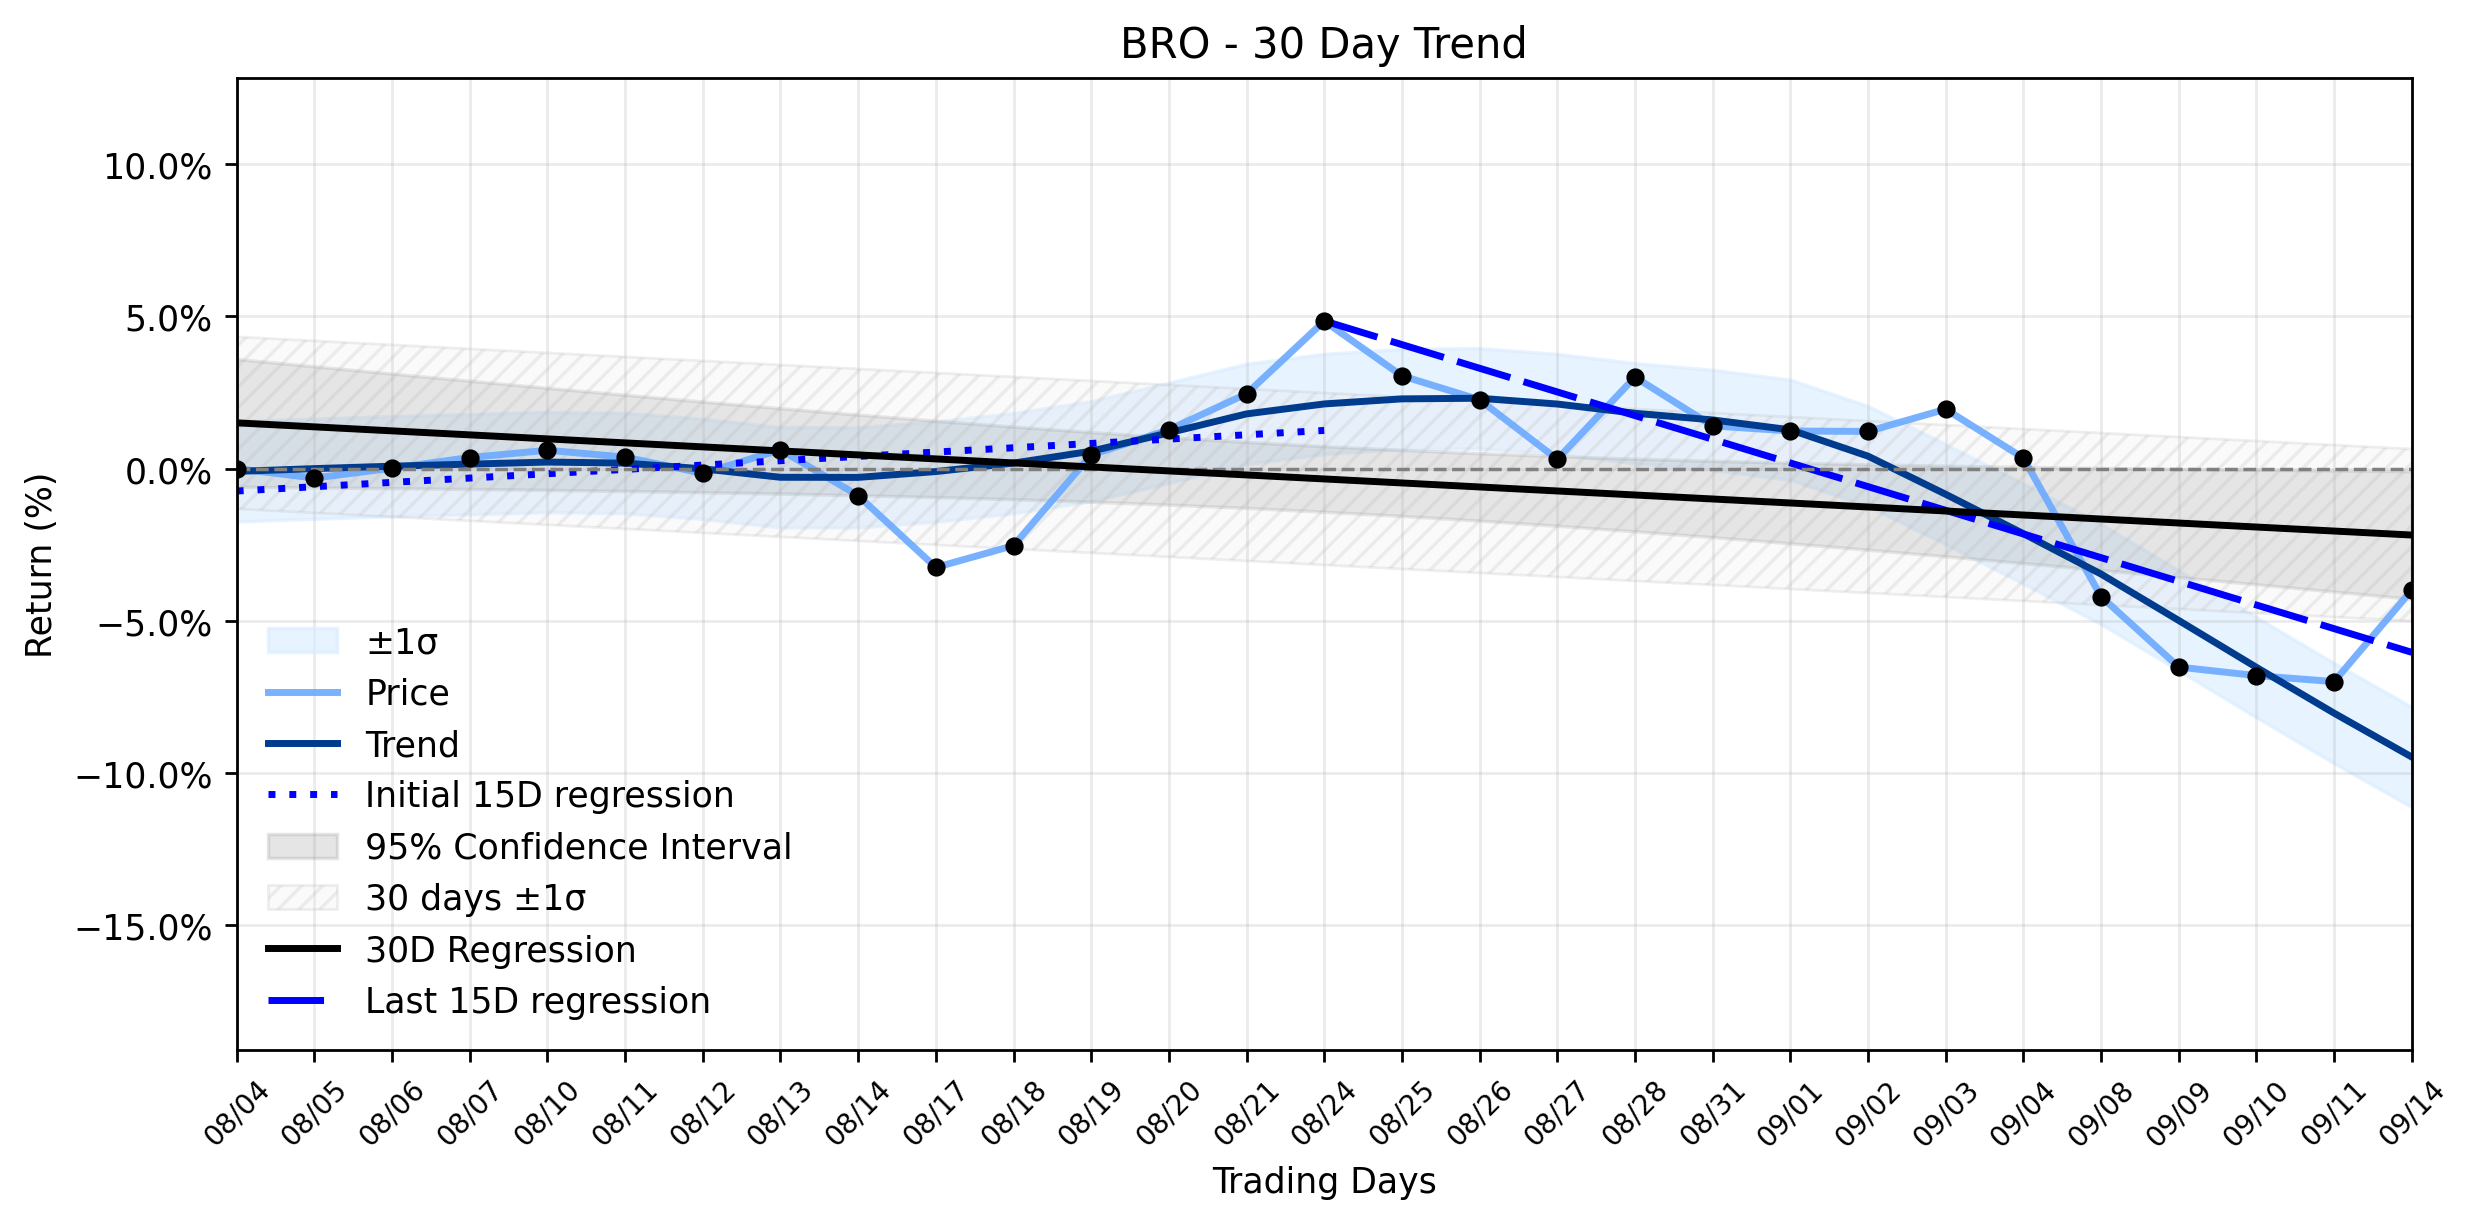
Pct Price Change: 3.23%
On the trading floor, Brown & Brown (BRO) opened at $66.19, climbed to a high of $68.70, and settled at a Close of $68.33, marking a significant Change of $2.14, or a 3.23% Pct Change. The companys Market Cap stood at a hefty $22,816,243,717. However, a deeper dive into the trend analysis reveals a more complex narrative. The earliest 15 trading days in the window (Days 1-15) showed a regression slope of 0.1422% per day, suggesting a slight upward drift. This was starkly contrasted by the most recent 15 trading days (Days 16-30), which registered a regression slope of -0.7778% per day. The overall ~30-day window (Days 1-30) reflected this decline with a slope of -0.1317% per day. The delta classification indicated insufficient data for a clear shift, yet the combined momentum classification firmly pointed to an Accelerating downtrend. This daily upward movement, therefore, appears to defy the prevailing gravitational pull of its recent performance.
The sudden upward thrust in BROs share price appears to be a confluence of several factors, momentarily overshadowing its underlying bearish trend. A significant catalyst was the broader rally in insurance brokerage stocks, sparked by news of a nearing $7.7 billion take-private deal for The Baldwin Insurance Group. This sector-wide enthusiasm likely provided a tailwind for Brown & Brown. Adding to the positive sentiment, GuruFocus highlighted that BRO is estimated to be 38.9% undervalued compared to its GF Value of $111.81, with its P/E (TTM) sitting 21% below its 5-year median. This deep undervaluation, coupled with a strong GF Score of 81/100 and positive insider buying activity, suggests that value investors might be starting to see an opportunity. Furthermore, Brown & Brown itself published content regarding the DOLs release of Field Assistance Bulletin No. 2026-03, outlining MHPAEA enforcement priorities, which could be interpreted as a sign of regulatory clarity or engagement within its operational landscape. While the companys Q2 2026 earnings had previously shown mixed results with a slight EPS miss and negative organic growth, management has reiterated expectations for improved organic growth in the second half of 2026, a long-term growth strategy, and investments in AI, as detailed in their 2026 investor presentation.
Looking ahead, the markets perception of Brown & Brown (BRO) remains a fascinating duality. The recent surge, fueled by sector M&A and compelling undervaluation metrics, offers a glimmer of hope for a stock caught in an accelerating downtrend. However, the underlying trend cannot be ignored. Investors will be watching closely to see if this green sign is the harbinger of a genuine reversal, or if the gravity of the accelerating downtrend will reassert itself, pulling the stock back into its established orbit. The battle between perceived intrinsic value and market momentum continues, a true clash of titans in the investment arena.
- https://finance.yahoo.com/quote/BRO/
- www.perplexity.ai/finance/BRO
- www.gurufocus.com/news/9080352/is-it-too-late-to-buy-brown-brown-inc-bro-after-32-rally-gf-value-says-undervalued
- www.marketscreener.com/news/brown-brown-dol-releases-fba-no-2026-03-outlining-mhpaea-enforcement-priorities-ce785bdcd18cf723
- www.investing.com/equities/brown---brown-inc
- www.stocktitan.net/sec-filings/BRO/8-k-brown-brown-inc-reports-material-event-be2f81294e87.html
- kalkinemedia.com/us/stocks/financial/is-brown-brown-nysebro-still-undervalued-after-pullback
More about Brown & Brown
Concept Map
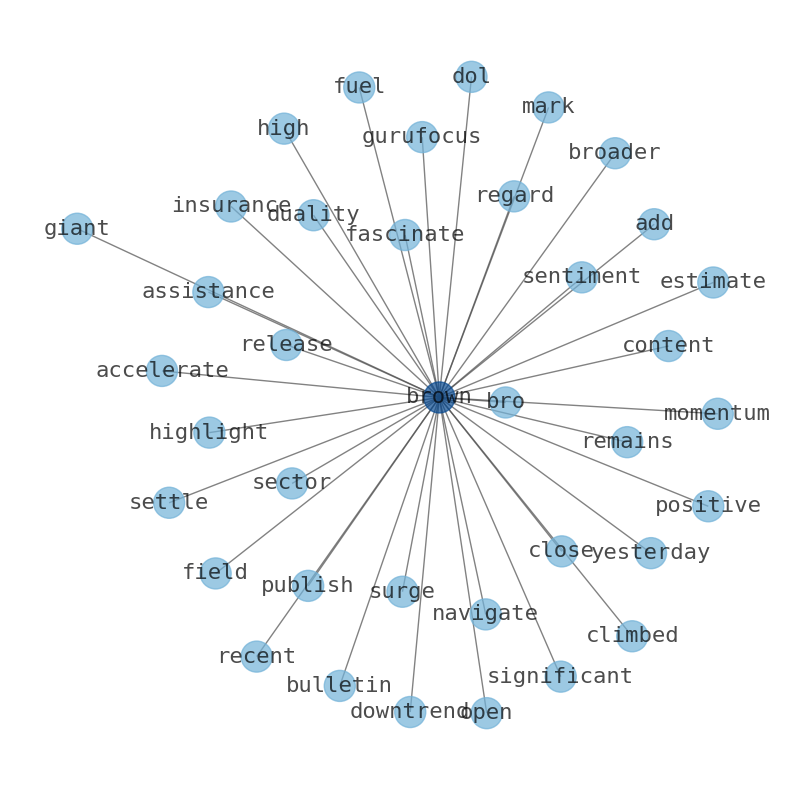
Semantic Network
WordCloud
Related Results
Brown & Brown (BRO) Flashes a Green Sign Amidst a Downtrend: Is Deep Undervaluation Fueling This Surge?
The financial markets, ever the arena of paradox, presented a curious spectacle for Brown & Brown (BRO) yesterday. Despite navigating an ac…
Brown & Brown (BRO) Pullback: Is the Stabilizing Uptrend Taking Shape for a Deeper Move, or a Rebound?
The markets recent session saw Brown & Brown (BRO) experience a slight pullback, a seemingly minor tremor that belies the underlying curren…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.