Five Point Holdings (FPH) in Quiet Freefall: Q3 Loss and Deferred Sales Signal Deeper Market Malaise
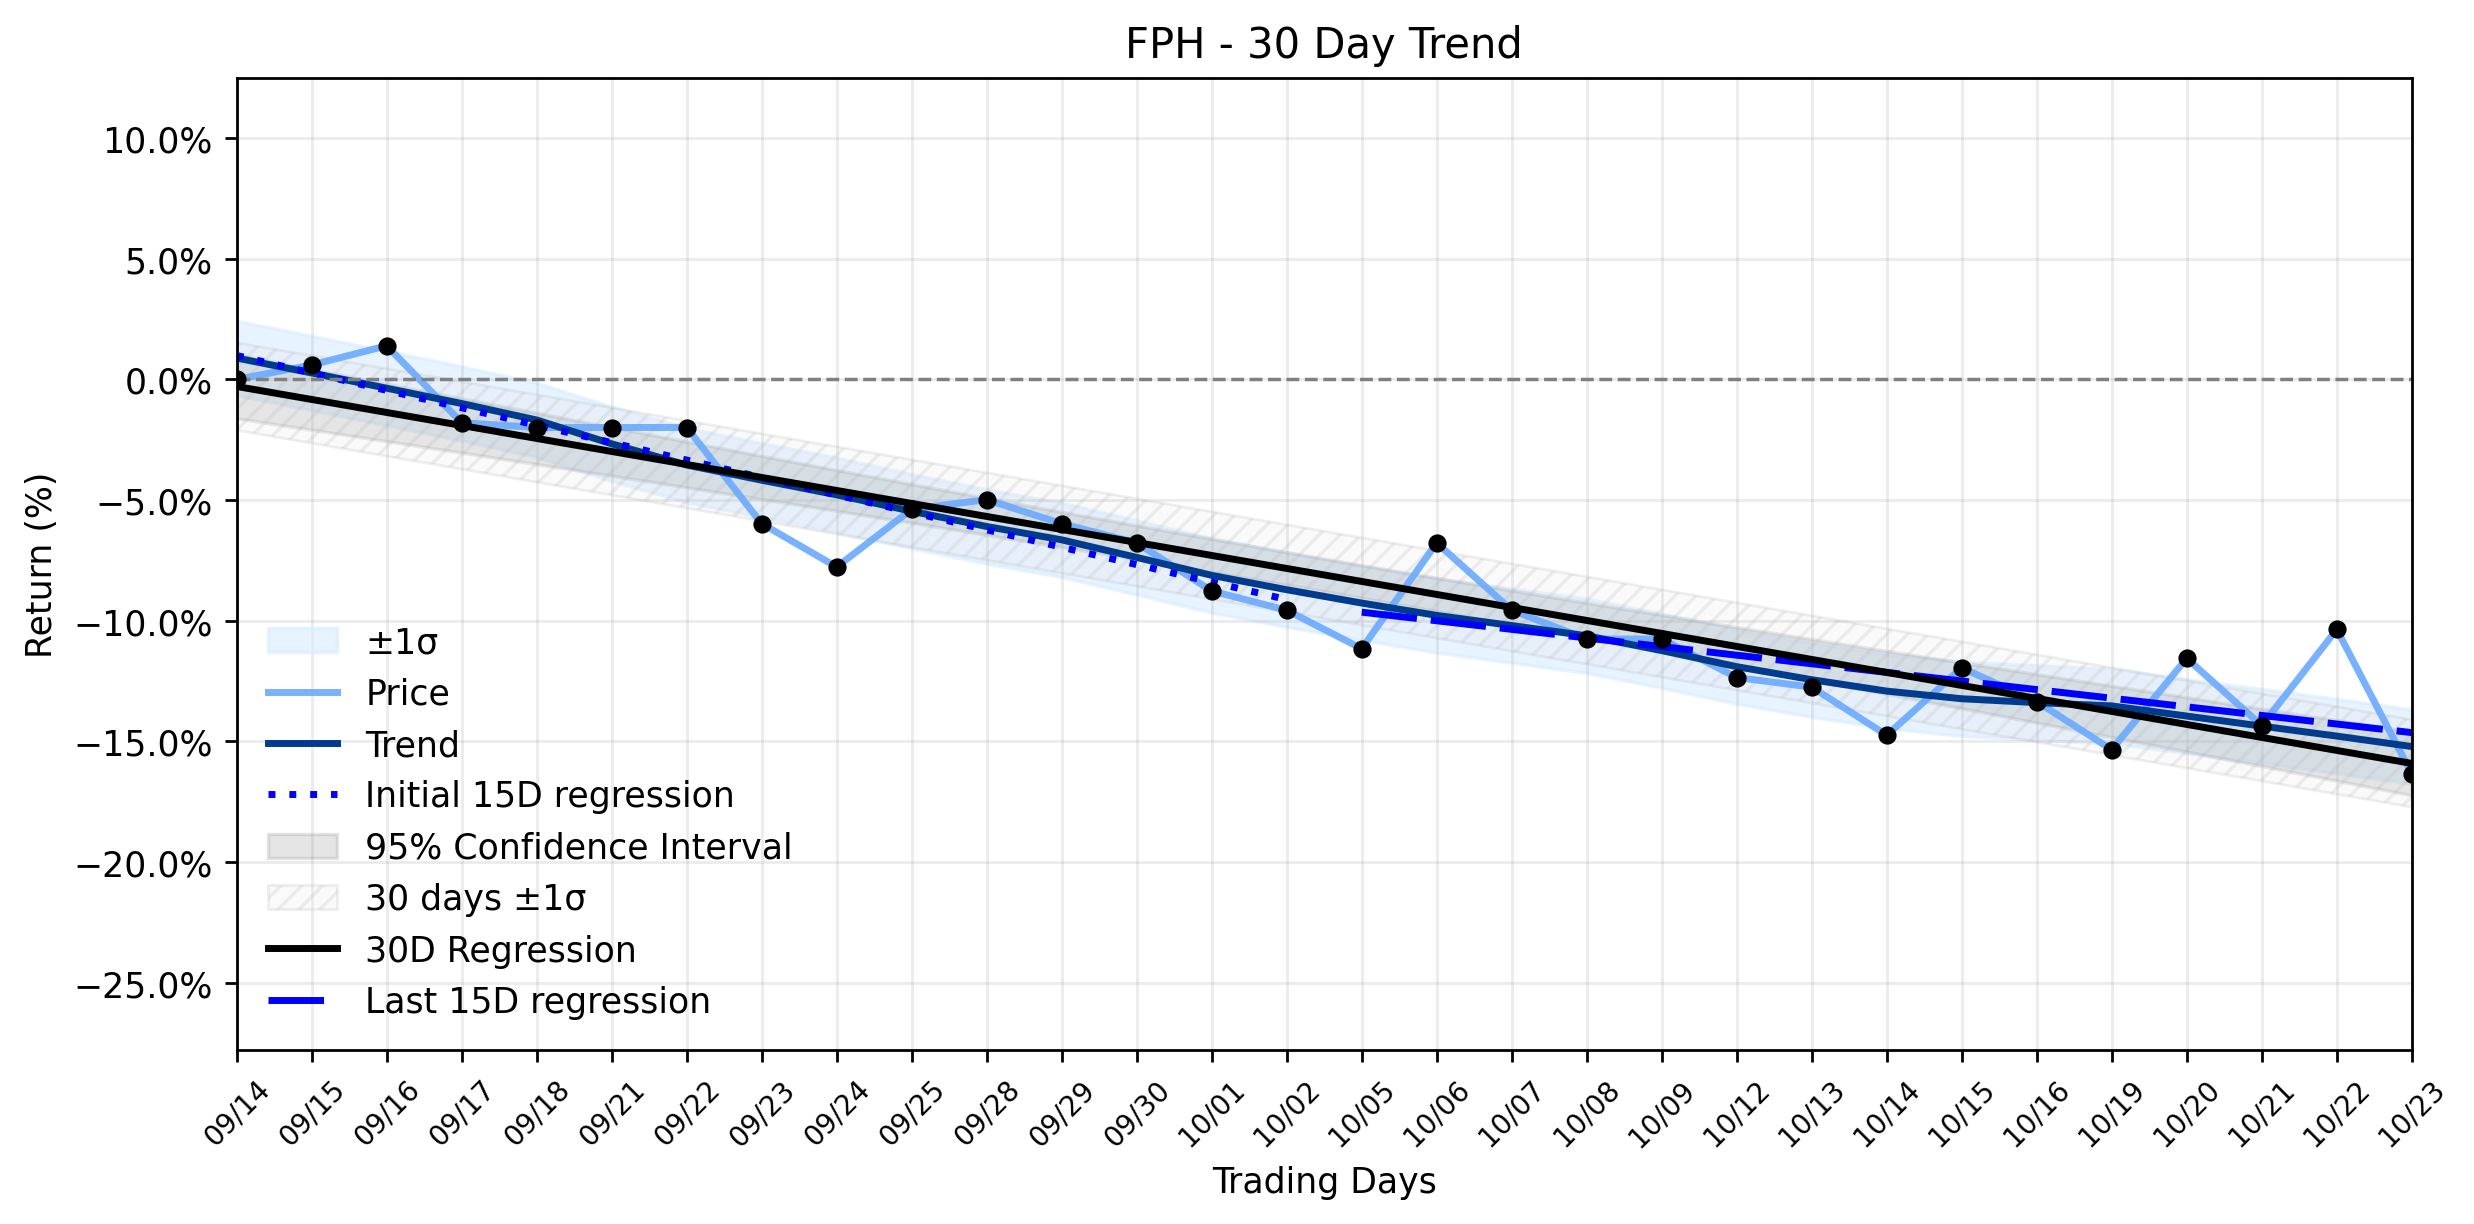
Pct Price Change: -6.67%
On October 23, 2026, Five Point Holdings announced its third-quarter 2026 results, reporting consolidated revenue of $14.6 million and a net loss of $4.4 million, translating to a loss of $0.04 per share. While the company managed to meet analyst consensus for earnings per share and even exceeded revenue estimates, the headline news was the absence of major land sale closings. Management explicitly stated a decision to defer anticipated land transactions into 2027, opting to preserve asset value rather than transact in a less favorable market characterized by slowing buyer absorption and elevated interest rates. This deferral led to a significant revision of its full-year 2026 net income guidance, slashed to approximately $20 million from a previous estimate of $100 million. Despite these operational headwinds, Five Point Holdings maintains a robust liquidity position of $576.2 million, including $358.7 million in cash, providing a buffer against market volatility.
The markets reaction to this strategic deferral and revised outlook was swift and unforgiving. FPH shares experienced a sharp plunge, closing at $4.2, down $0.3 or -6.67% from its previous close. The stock traded as low as $4.09, hitting a new 52-week low of $4.11 during the day. This daily performance starkly confirms the prevailing Stable downtrend identified in the companys recent trading patterns. Over the earliest 15 trading days in the ~30-day window, FPH exhibited a regression slope of -0.7221% per day, which slightly improved to -0.3564% per day in the most recent 15 trading days. However, the overall ~30-day window still shows a negative regression slope of -0.5385% per day, indicating a persistent downward trajectory. The insufficient data for delta classification suggests that while the rate of decline might have moderated slightly, it hasnt fundamentally shifted the bearish sentiment. With a market capitalization now standing at $301,585,530, the company faces a challenging environment where even strategic patience comes at a price. Analysts, such as Weiss Ratings, currently maintain a Hold rating, while GuruFocus suggests the stock is significantly overvalued at its current price relative to its intrinsic value, adding another layer of caution to the investment thesis. The deferral of sales, while perhaps prudent for long-term asset value, signals a broader struggle within the housing market, where high interest rates continue to cool buyer enthusiasm and force developers to play a waiting game.
- https://finance.yahoo.com/quote/FPH/
- www.marketbeat.com/instant-alerts/price-five-point-nyse-fph-reaches-new-1-year-low-time-to-sell-2026-10-23/
- www.gurufocus.com/news/9139109/five-point-holdings-fph-reports-q3-2026-revenue-of-146m-with-net-loss-amid-deferred-land-sales
- www.fool.com/earnings/call-transcripts/2026/10/22/five-point-holdings-fph-q3-2026-earnings-call-transcript/
- finance.biggo.com/quote/FPH/earnings-call/US_FPH_2026-10-22
- seekingalpha.com/news/4656426-five-point-expects-about-20m-2026-net-income-while-deferring-land-sales-into-2027
- www.gurufocus.com/news/9140304/five-point-holdings-llc-fph-q3-2026-earnings-call-highlights-deferred-land-sales-and-a-revised-outlook
- seekingalpha.com/article/4956683-five-point-holdings-llc-fph-q3-2026-earnings-call-transcript
More about Five Point Holdings LLC
Concept Map
Semantic Network
WordCloud
Related Results
Five Point Holdings (FPH) in Quiet Freefall: Q3 Loss and Deferred Sales Signal Deeper Market Malaise
The real estate sector, particularly in the high-stakes arena of coastal California development, often resembles a strategic game of chess,…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.