Mueller Water Products (MWA) Posts Impressive Gain: Why You Need to Quickly Understand Its Strategic Shift
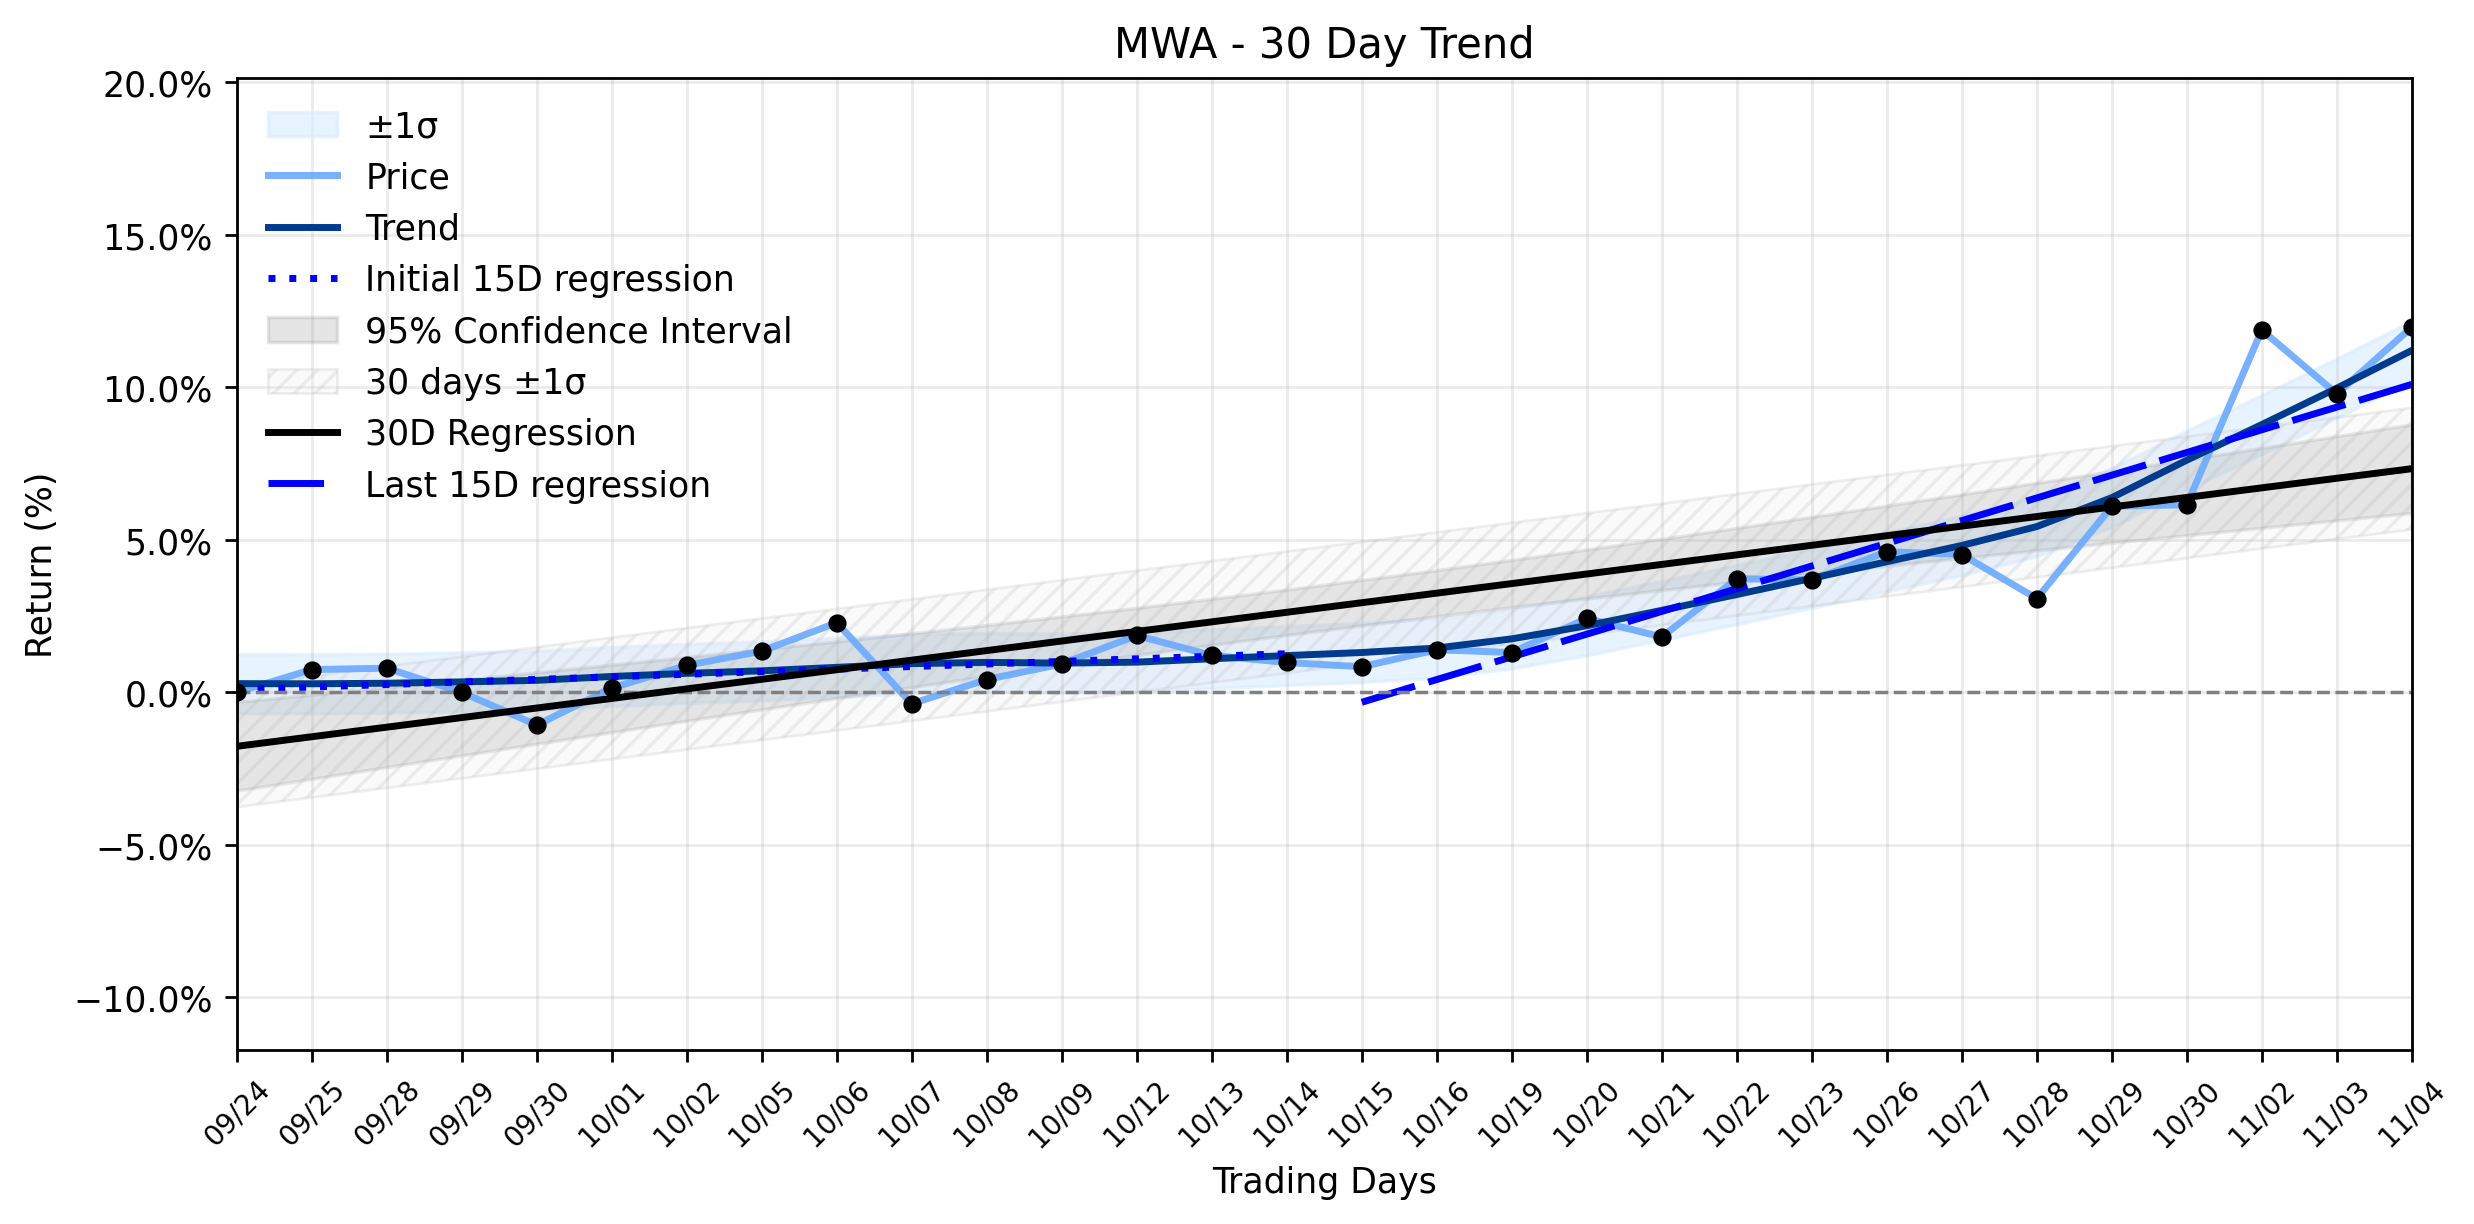
Pct Price Change: 1.99%
The markets reaction was notably positive, with MWAs stock closing up 1.99%. This upward movement was likely fueled by several key announcements beyond the raw earnings figures. Mueller Water Products revealed an agreement to transition its metering business, operated through its Mueller Systems subsidiary, to ZENNER USA. This strategic divestiture is intended to streamline the companys portfolio, allowing it to concentrate capital and management focus on areas with stronger competitive advantages and clearer growth prospects. Furthermore, the company sweetened the deal for shareholders by increasing its quarterly dividend by 14.3% to $0.08 per share and authorizing a new $300 million share buyback program, signaling confidence in its future and a commitment to returning value.
On the trading floor, MWA opened at $23.57 and reached a high of $24.33 before settling at a close of $24.04. The days low was $23.20. The stock experienced a change of $0.47, translating to a 1.99% increase. Volume surged to 3,211,200 shares, significantly higher than its average, indicating robust investor interest. The companys market capitalization stood at $3,753,261,466.
Analyzing this daily performance within the broader trend reveals an interesting dynamic. The stocks recent trajectory shows an accelerating uptrend, with the Days 16-30 regression slope at 0.7442% per day, a substantial increase from the Days 1-15 slope of 0.0842% per day. This suggests that the bullish momentum has been building over the latter half of the ~30-day window. While the Delta classification is noted as insufficient data, the Combined momentum classification clearly identifies an Accelerating uptrend, which the days impressive gain strongly confirms. The market appears to be rewarding the companys proactive steps to optimize its business and enhance shareholder returns, aligning with the strengthening positive trend.
The understanding twist here is that the market seems to be playing a long game, looking past the minor revenue dip and focusing on the strategic repositioning. In an era where operational efficiency and focused growth are paramount, shedding a non-core asset like the metering business, despite incurring one-time expenses of approximately $26 million in fiscal 2027, is perceived as a shrewd move. The anticipated annualized adjusted EBITDA margin benefit of 100 to 140 basis points from this transition, primarily beginning in fiscal 2027s second quarter, paints a picture of future profitability. Coupled with the increased dividend and share buyback, Mueller Water Products is effectively signaling to the market that it is streamlining for battle, fortifying its core, and preparing for a more profitable campaign ahead, turning a seemingly mixed earnings report into a rallying cry for its accelerating uptrend.
- https://finance.yahoo.com/quote/MWA/
- www.marketbeat.com/instant-alerts/earnings-mueller-water-products-nyse-mwa-announces-quarterly-earnings-results-hits-expectations-2026-11-04/
- www.investing.com/news/earnings/mueller-water-products-earnings-matched-revenue-fell-short-of-estimates-5001577
- www.zacks.com/stock/news/3023603/mueller-water-products-mwa-misses-q4-earnings-and-revenue-estimates
- tickeron.com/blogs/mueller-water-products-mwa-delivers-record-full-year-sales-amid-mixed-quarterly-results-28826/
- www.stocktitan.net/news/MWA/mueller-water-products-announces-agreement-to-transition-metering-uy4emim29aap.html
- markets.businessinsider.com/news/stocks/mueller-water-products-announces-agreement-to-transition-metering-business-to-zenner-usa-1036717203
- www.globenewswire.com/news-release/2026/11/04/3395848/0/en/Mueller-Water-Products-Reports-Record-Fourth-Quarter-and-Full-Year-2026-Results-Introduces-Fiscal-2027-Guidance.html?f=22&fvtc=5&fvtv=33113660
- stocktwits.com/symbol/MWA
- www.stocktitan.net/sec-filings/MWA/8-k-mueller-water-products-inc-reports-material-event-c8a6ca03bb7b.html
More about Mueller Water Products
Concept Map
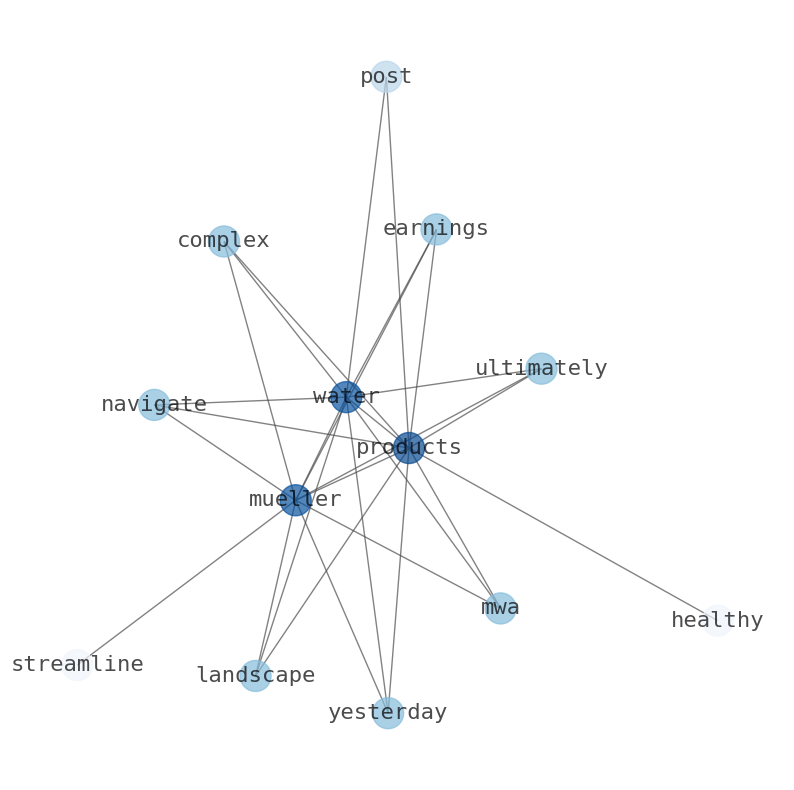
Semantic Network
WordCloud
Related Results
Mueller Water Products (MWA) Posts Impressive Gain: Why You Need to Quickly Understand Its Strategic Shift
Mueller Water Products (MWA) navigated a complex earnings landscape yesterday, ultimately posting a healthy climb as investors digested a s…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.