Progyny (PGNY) Sees Sharp Rise: Is Wells Fargo Spotting a Reversal in the Accelerating Downtrend You Need to Know Quickly?
Pct Price Change: 1.53%
The markets reaction to this analyst interest was palpable, with PGNY opening at $24.85 and reaching a high of $25.45 before closing at $25.23. This pushed the stock up by $0.38, culminating in a market capitalization of $1,935,817,078. The days trading volume stood at 939,600, indicating a decent level of activity for the fertility and family-building benefits provider. This daily uptick, however, serves as a fascinating counterpoint to the stocks recent trajectory.
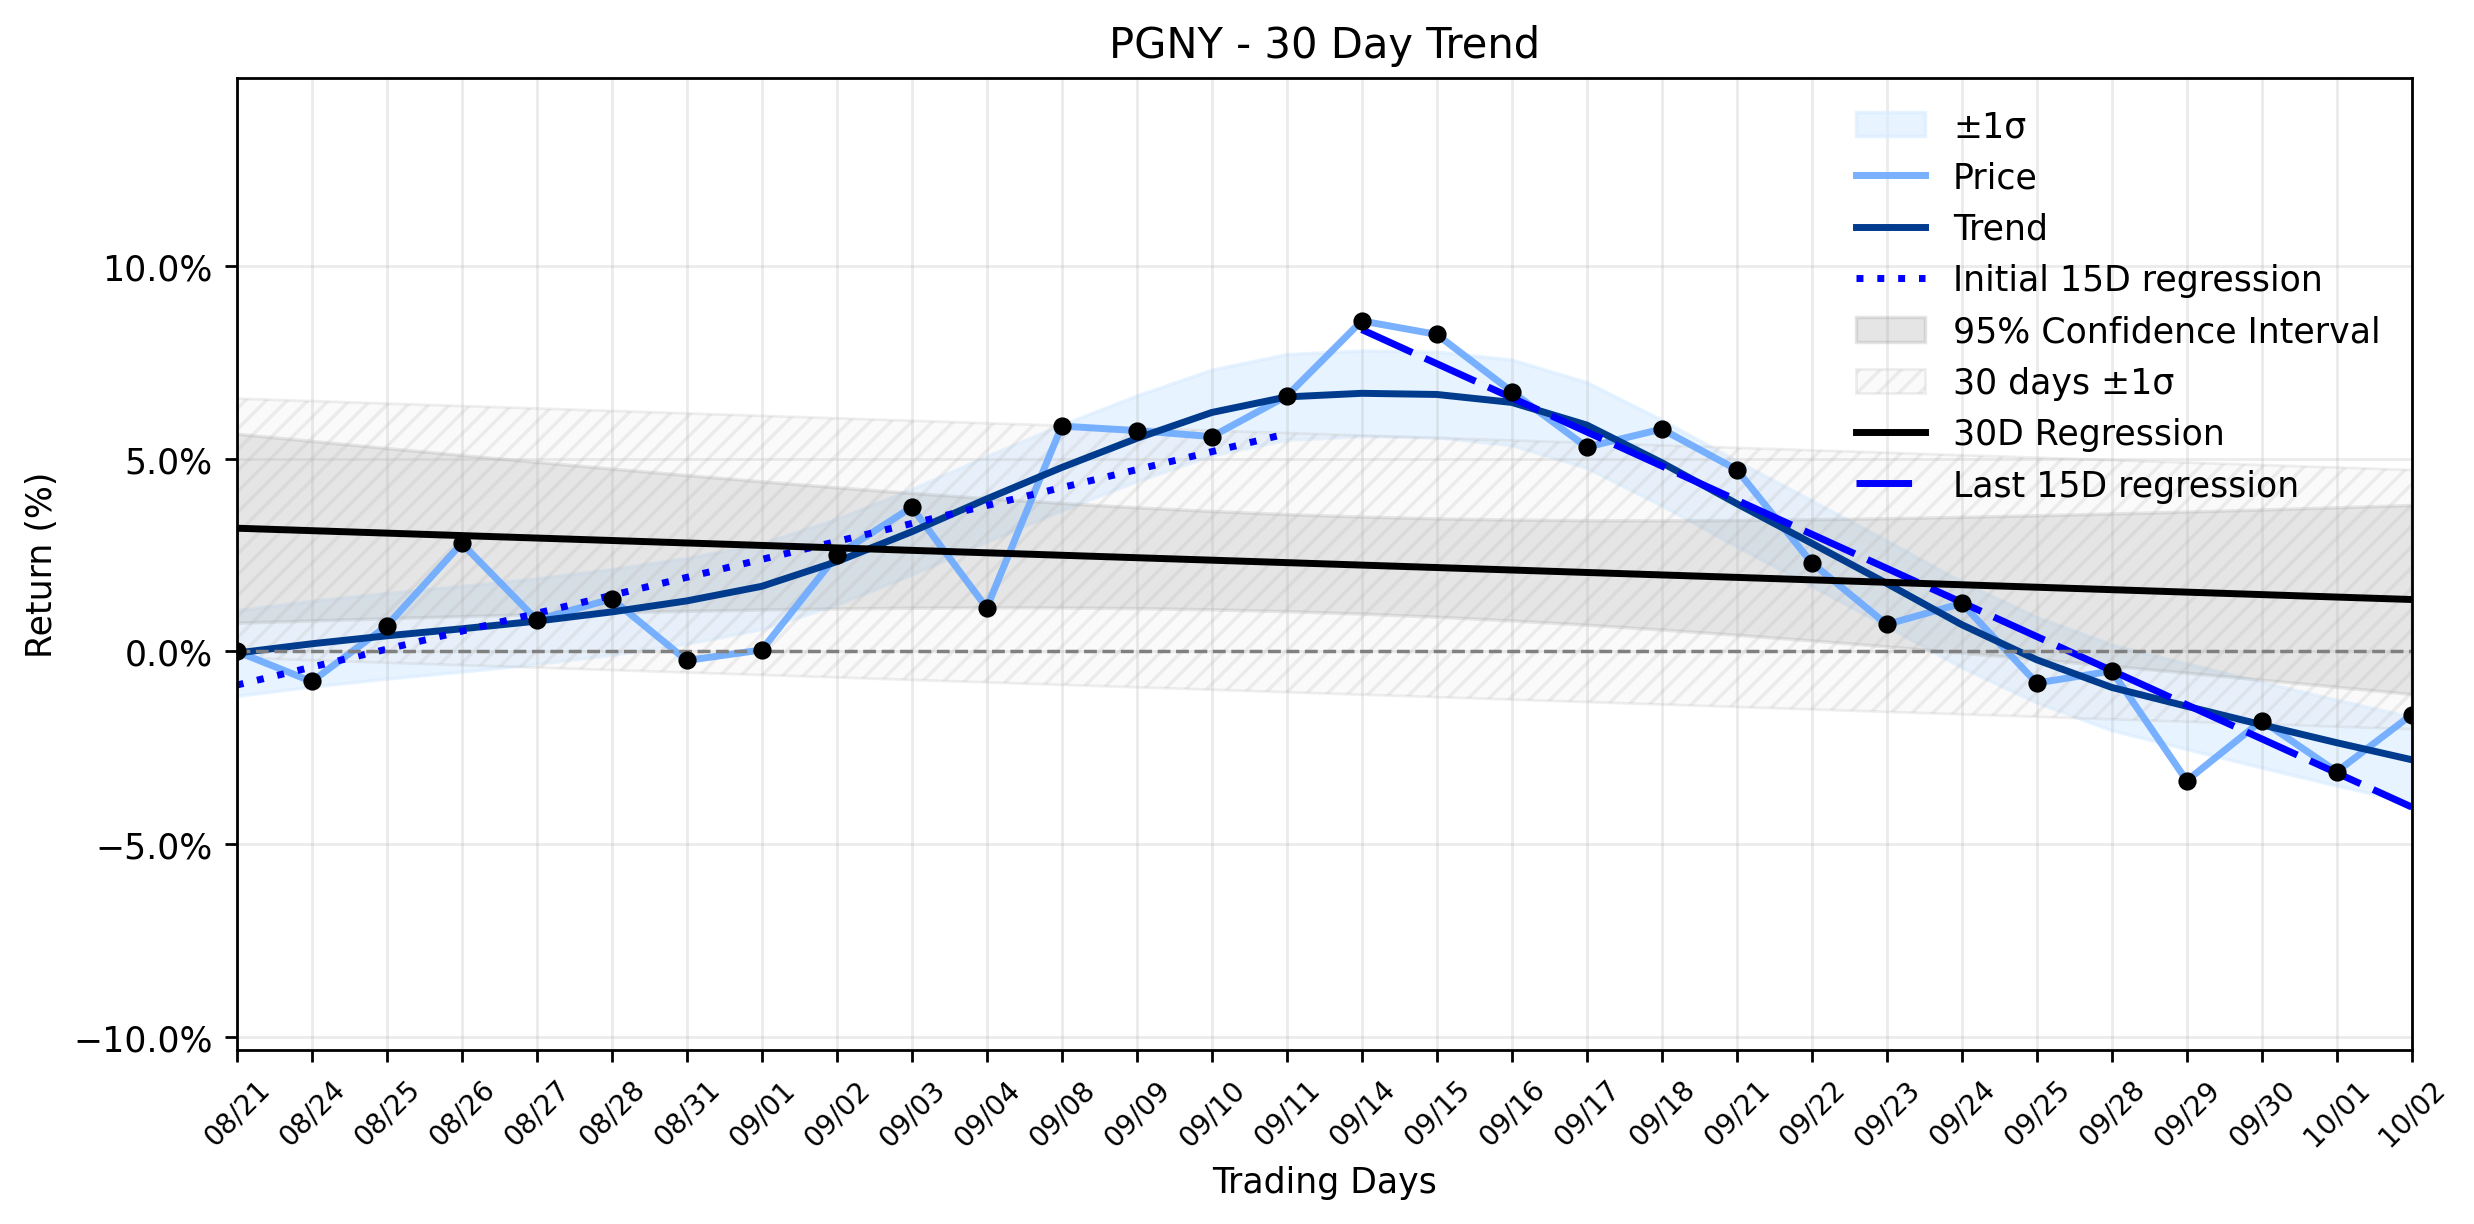
Delving into the deeper market currents, Progynys trend analysis paints a more complex picture. While the earliest 15 trading days in the window showed a positive regression slope of 0.4659% per day, the most recent 15 trading days have seen a stark reversal, with a regression slope plummeting to -0.8851% per day. This dramatic shift has earned PGNY a Combined momentum classification of an Accelerating downtrend. The Delta classification remains insufficient data, leaving investors to ponder the true inflection point. The overall 30-day trend, represented by a regression slope of -0.0638% per day, confirms a slight negative bias despite the initial bullish spurt.
This daily surge, therefore, appears less like a triumphant charge and more like a tactical skirmish win in a prolonged war. While Wells Fargos reported interest might ignite short-term optimism, the accelerating downtrend suggests that the broader gravitational pull is still downwards. Recent news from August 2026 indicated Progyny reported strong second-quarter results, surpassing Wall Street expectations, yet simultaneously warned of a more pronounced summer slowdown. This conservative guidance, coupled with insider selling activity reported in September, where an EVP sold 3,903 shares and a director sold 11,500 shares, could be contributing factors to the underlying bearish momentum. The companys ongoing share repurchase program, including a new $200 million authorization in May 2026, aims to bolster shareholder value. Yet, even with these efforts, the markets long-term sentiment seems to be grappling with the companys growth narrative versus its operational realities and broader economic headwinds. Investors are left to discern whether yesterdays impressive gain is the first spark of a genuine reversal or merely a fleeting moment of defiance against a prevailing tide.
- https://finance.yahoo.com/quote/PGNY/
- www.marketbeat.com/stocks/NASDAQ/PGNY/
- www.investing.com/news/insider-trading-news/progyny-director-kevin-gordon-sells-311858-in-shares-93CH-4907983
- www.fool.com/investing/2026/08/07/why-progyny-stock-dipped-today/
- www.stocktitan.net/news/PGNY/
- www.stocktitan.net/news/PGNY/progyny-inc-announces-share-repurchase-tgao3y968wea.html
More about Progyny
Concept Map
Semantic Network
WordCloud
Related Results
Progyny (PGNY) Sees Sharp Rise: Is Wells Fargo Spotting a Reversal in the Accelerating Downtrend You Need to Know Quickly?
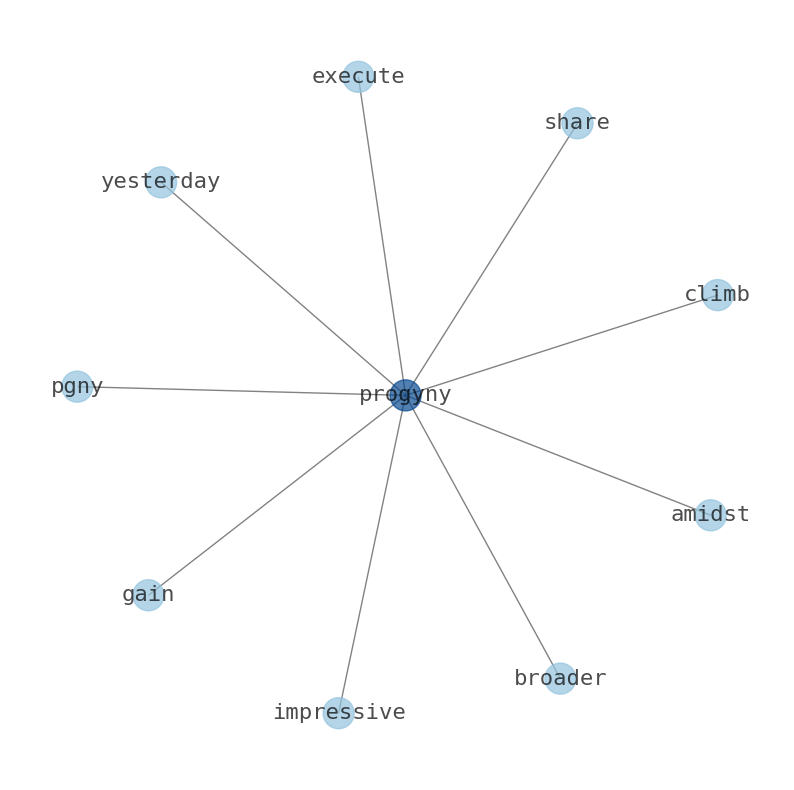
The markets intricate dance saw Progyny (PGNY) execute an impressive gain yesterday, with shares climbing 1.53% amidst a broader narrative …
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.